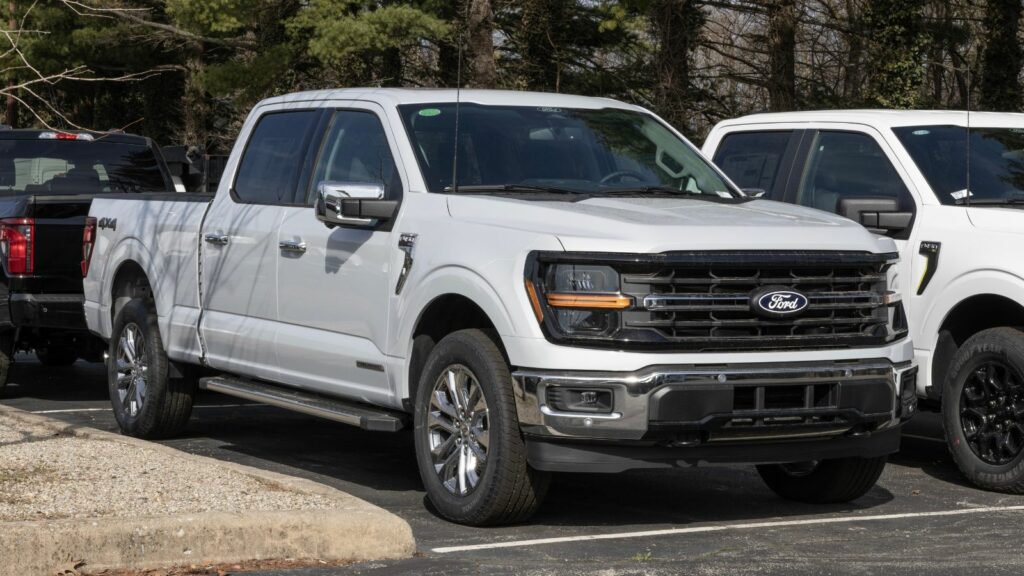
Canadian vehicle showrooms are revealing a complicated shift in what drivers buy. Sales of large pickup trucks fell 4.1% during the first nine months of 2026, according to DesRosiers Automotive Consultants, even as SUVs and other light trucks continued to dominate new-vehicle purchases. The broader light-truck category accounted for 87.2% of sales, leaving passenger cars with only 12.8%.
Those figures describe a market changing at different speeds. Some SUV segments are growing, others are struggling, and pickup sales have shown signs of stabilizing after a difficult start to the year. Meanwhile, higher vehicle costs and economic uncertainty are making the decisions facing both buyers and dealerships more complicated.
The Pickup Decline Is Real, but the Pace Has Eased
Large pickup trucks posted a 4.1% sales decline from January through September 2026 compared with the same period in 2025. That was the steepest drop among Canada’s six highest-volume vehicle segments, according to DesRosiers Automotive Consultants. It is a meaningful setback for a category associated with everything from construction crews and farming to family transportation. But the figure describes a change in sales, not the share of Canadians who own pickups, and it does not mean that one in 25 pickup owners has abandoned a truck.
The direction within the year is also important. Large-pickup sales were down 5.8% in the first six months, yet their third-quarter decline narrowed to just 0.7% compared with July through September 2025. That suggests the segment was closer to steady in the summer than it had been earlier. A contractor who needs towing capability may still have few practical substitutes, while another household might reconsider the cost of a full-size truck. The published totals cannot determine why individual purchasers acted, but they show a slowdown rather than a uniform collapse.
The 87.2% Figure Covers Much More Than SUVs
The most dramatic percentage in the latest figures is also the easiest to misread. Light trucks accounted for 87.2% of Canadian new light-vehicle sales through September, while passenger cars held 12.8%. In automotive market reporting, light trucks are a broad classification that includes SUVs, crossovers, pickup trucks and vans. Statistics Canada’s vehicle definitions distinguish these body types, even though they may be combined for a headline market-share measure. Saying SUVs alone claimed 87.2% would therefore overstate their share.
The distinction changes the interpretation. A compact crossover bought for school runs, a work pickup carrying equipment and a minivan transporting several children can all contribute to the light-truck side of the ledger. Nor does the figure mean that 87.2% of vehicles already on Canadian roads are light trucks; it refers to new sales during a defined period. For context, light trucks represented 87.8% of sales in the first half of 2026, so the nine-month share was slightly lower. Their dominance remains unmistakable, but the newest number is not evidence that their share rose continuously all year.
Compact SUVs Remain the Market’s Centre of Gravity
Compact SUVs are still Canada’s largest new-vehicle segment, making their performance especially important to the broader market. Their sales were down 4.3% in the first half of 2026, according to DesRosiers, but rebounded by 7% year over year during the third quarter. By the end of September, the year-to-date decline had narrowed to 0.6%. That is a substantial change in momentum, although it falls short of showing that the segment was growing for the full nine-month period.
The appeal of a compact SUV is easy to understand in everyday terms: it can offer passenger seating, a useful cargo area and a footprint more manageable than that of a full-size pickup. Those characteristics make the category relevant to households balancing commuting with grocery trips, sports equipment and weekend travel. Still, practical appeal should not be mistaken for proof of what caused the sales rebound. The data establish that more compact SUVs were sold in the third quarter than in the comparable quarter a year earlier; they do not isolate whether new models, financing offers or pent-up demand drove those purchases.
The SUV Boom Has Winners and Losers
Not every SUV category is moving in the same direction. Intermediate SUVs recorded a 3.2% sales increase through September, the strongest result among Canada’s six largest vehicle segments. Compact luxury SUVs gained 0.3%, while subcompact SUVs were down 1.2% after a softer third quarter. These are modest percentage changes, but they matter because they challenge the idea of a single, unstoppable surge affecting every vehicle sold with an SUV badge.
For buyers, the segments represent different decisions. A household comparing an intermediate SUV with a smaller crossover may be weighing rear-seat room, cargo needs, parking space and the size of the monthly payment. A luxury buyer faces yet another set of choices. The fact that intermediate SUVs are doing relatively well does not prove that purchasers are upgrading from subcompact models, or that larger vehicles have become cheaper. The segment report does not track those individual trade-ins or switching decisions. It simply shows that, within the overall preference for light trucks, demand is uneven and size categories can move in opposite directions.
Registration Figures Tell a Different Part of the Pickup Story
Statistics Canada offers a useful cross-check on vehicle demand, although its figures measure registrations rather than the same sales categories used by DesRosiers. In the second quarter of 2026, Canadians registered 547,673 new motor vehicles, up 1.1% from a year earlier. Pickup-truck registrations declined 0.5%, the only vehicle type in that release to record a decrease. By contrast, van registrations rose 10.1%, passenger cars gained 2.1% and multipurpose vehicles, including SUVs and crossovers, edged up 0.7%.
These figures are not in conflict with the 4.1% decline in large-pickup sales. Statistics Canada’s pickup category includes more than the large trucks singled out by DesRosiers, and the federal release covers April through June rather than the first nine months of the year. Registrations and sales also come from different reporting systems. That distinction may sound technical, but it prevents an important misunderstanding: a modest decline for all pickups in one quarter does not cancel a steeper nine-month decline for the large-pickup segment. Both point to softness, measured through different lenses.
Passenger Cars Have Lost Ground, Not Relevance
Passenger cars made up only 12.8% of Canada’s new light-vehicle market through September, and sales were 1.3% below the same nine-month period in 2025. Yet the smaller market share conceals some surprisingly mixed results. Compact passenger cars enjoyed a strong third quarter, although their earlier losses still left them down for the year. In the first half, intermediate passenger-car sales had climbed 24%, supported by stronger demand for models including the Toyota Camry and Prius.
At the other extreme, subcompact car sales plunged 64.3% during the first half, when DesRosiers said fewer than 2,000 vehicles were sold across a segment reduced to two models. This helps explain why percentage swings in small categories can look spectacular without reshaping the entire market. For someone seeking an efficient commuter car, a sedan or hatchback may still make more sense than a larger vehicle. The challenge is that the choices available are not equally broad across every car segment. Canada’s passenger-car market is diminished, but treating it as entirely abandoned misses the areas where demand persists.
September’s Recovery Has Not Erased the Whole Year
September provided one of the more encouraging signals for Canadian dealerships. DesRosiers estimated that about 168,000 new light vehicles were sold, up 3.4% from roughly 163,000 in September 2025. It was the fourth consecutive month of year-over-year sales growth. After accounting for an extra selling day in September 2026, the market’s seasonally adjusted annualized sales rate stood at approximately 1.91 million vehicles, which DesRosiers described as within its recent range.
The brighter monthly result needs a longer view. Sales across the first nine months of 2026 were still 0.7% below the comparable period last year. A family taking delivery of an SUV in September contributes to the stronger month, but that purchase does not erase weaker sales recorded earlier in the year. Nor does four months of annual gains necessarily imply that every manufacturer or vehicle category improved. The distinction between a recovering monthly pace and a slightly negative year-to-date total is central to understanding why the overall market can look resilient while large pickups remain down.
Price Pressure Gives the Sales Numbers a Human Dimension
Buying a new vehicle remains a major household commitment, whatever body style sits on the driveway. Statistics Canada counted 176,156 new motor vehicles sold in July 2026, a 2% decline in units from July 2025, even as the total dollar value of sales rose 1.6%. Newfoundland and Labrador’s Department of Finance, analyzing the national statistics, reported that the average price per new vehicle sold in Canada reached $57,249 that month, up 3.7% year over year.
That average is not a price tag attached to every car on a lot. It is influenced by the mixture of vehicles actually sold, including more expensive pickups and SUVs, and does not isolate price changes for identical models. Nevertheless, it illustrates why even a relatively small shift in demand matters for families planning a purchase. Loan payments are only one part of the equation; insurance, fuel, tires and maintenance also enter the household budget. The figures do not prove that affordability caused the pickup decline, but they help explain why shoppers may compare vehicle size and total ownership costs more carefully.
Hybrids and EVs Are Reshaping Choices Within Body Styles
Vehicle size is only one dimension of Canada’s changing auto market. In the second quarter of 2026, new registrations of conventional hybrid-electric vehicles jumped 39.5% from a year earlier, while battery-electric registrations grew 37.4% and plug-in hybrid registrations increased 8%. Statistics Canada reported 58,811 new zero-emission vehicle registrations in the quarter, accounting for 10.7% of all new registrations, up from 8.6% one year earlier. The zero-emission measure includes battery-electric and plug-in hybrid vehicles, but not conventional hybrids.
This matters because an SUV can be gasoline-powered, hybrid or fully electric and still count as an SUV. The 87.2% light-truck share therefore says nothing by itself about how many Canadians are choosing electric powertrains. Someone shopping for a crossover can be deciding both how much cargo space is needed and whether charging access makes an EV practical. Those choices intersect, but the available national releases do not establish that rising electrified-vehicle registrations caused large-pickup sales to weaken. The clearest conclusion is that body style and powertrain are two separate, overlapping stories.
Regional Differences Complicate the National Picture
Canada’s vehicle market rarely moves in lockstep across provinces. DesRosiers reported that nine of 10 provinces recorded year-over-year new-vehicle sales growth in August 2026. Ontario’s sales rose 7.1%, Quebec’s increased 4.1%, and Manitoba registered an 18.9% gain. Prince Edward Island was the exception, with sales down 11.9%. Yet through August, only Nova Scotia and Quebec were ahead of their 2025 year-to-date totals, showing how a strong summer could coexist with earlier weakness.
Those provincial percentages also need perspective. A sizeable percentage change in a smaller market does not necessarily contribute as many vehicles to the national total as a more modest move in Ontario. It would be equally risky to use these figures to declare that pickups are losing favour in any particular province; they refer to overall vehicle sales, not pickup-specific demand. A farm business replacing a work truck and an urban family looking for a smaller crossover have different requirements, but the provincial figures do not identify those individual decisions. They show that nationwide averages conceal a patchwork of local conditions.
Trade Tensions Add Another Layer of Uncertainty
Canadian dealerships and manufacturers are navigating more than a routine change in consumer tastes. DesRosiers has repeatedly pointed to geopolitical disruption, elevated fuel costs and Canada–U.S. trade friction as part of the difficult backdrop for 2026. In August, the Automobile Protection Association warned that tariff escalation could affect Canadian-assembled vehicles and raise the costs of vehicles assembled in the United States using cross-border parts. That uncertainty matters to an industry whose vehicles and components move through deeply integrated North American supply chains.
Still, the headline pickup decline should not be attributed automatically to tariffs. The segment figures do not break out how many sales were lost because of border measures, financing conditions or changing vehicle preferences. What dealers can see more directly is the need to plan around a market that is neither booming nor collapsing. Stocking too many expensive trucks poses one kind of risk; having too few of the SUVs that customers want poses another. In that environment, the difference between a 4.1% nine-month decline and a 0.7% third-quarter dip becomes operationally important, even without a definitive explanation for the shift.
The Final Quarter Will Test Whether Stability Holds
The remaining months of 2026 could clarify whether large pickups have found firmer ground or merely experienced a temporary summer reprieve. DesRosiers has cautioned that the fourth quarter faces tougher comparisons because sales were relatively strong near the end of 2025. It has also identified changing zero-emission-vehicle incentives and the possible arrival of Chinese automotive brands as developments to watch. Neither factor guarantees a particular outcome, but both could influence which models attract attention before year-end.
For the market as a whole, several signals will be more useful than one dramatic percentage: whether compact SUVs keep their third-quarter momentum, whether intermediate SUVs maintain growth, whether passenger cars continue recovering and whether pickup declines narrow further. Those measures should be assessed alongside total sales, rather than substituted for them. The latest data portray a Canadian market strongly oriented toward SUVs and other light trucks, but not one where every large vehicle is winning. Pickup sales are weaker, consumers still have varied needs, and the more important story may be a reshuffling within an overwhelmingly light-truck market.
