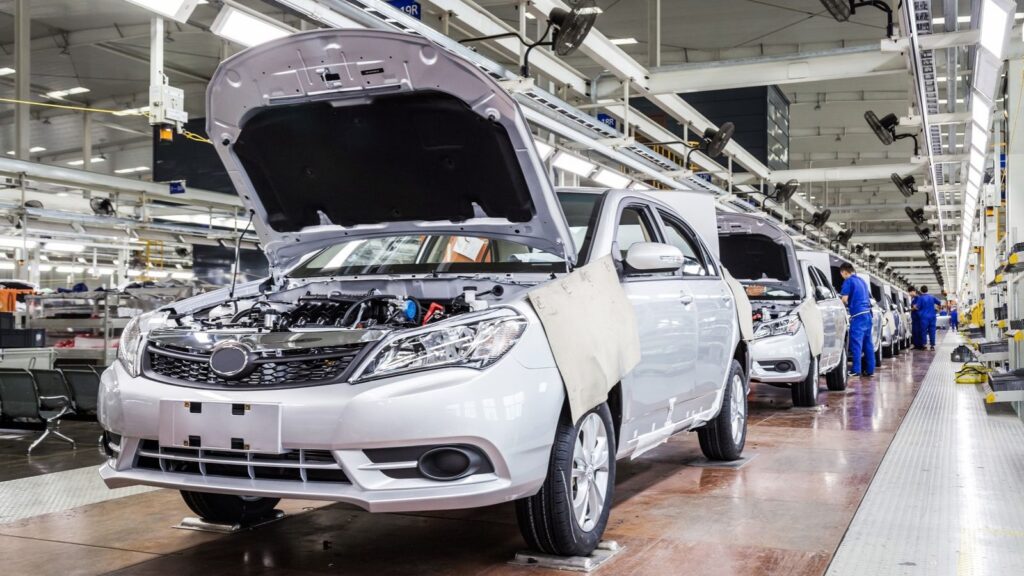
Canada’s automotive industry delivered two sharply different results in August 2026. Economic activity in motor vehicle and parts manufacturing contracted by 5.8%, while activity at motor vehicle and parts dealerships increased by 1.8%, according to Statistics Canada figures released on October 30. The contrast highlights a widening gap between the country’s vehicle production operations and its retail automotive market.
A prolonged summer shutdown at a major assembly plant contributed to weaker manufacturing output, even as stronger new-car sales helped dealerships recover from July’s slowdown. With Canada’s overall economy recording virtually no growth for a second consecutive month, the automotive figures reveal an industry navigating production interruptions, uneven supply chains, and changing consumer demand.
The 5.8% Drop Measures Output, Not the Number of Cars Built
Statistics Canada’s 5.8% decline refers specifically to real gross domestic product in motor vehicle and parts manufacturing in August, compared with July. It is not a count of vehicles rolling off assembly lines, nor does it mean every Canadian manufacturer produced 5.8% less. GDP by industry measures the inflation-adjusted value created by businesses. The figures are seasonally adjusted, helping analysts distinguish unusual changes from predictable swings in the calendar.
The weakness was significant enough to pull transportation equipment manufacturing down 3.1%, even though manufacturing overall expanded slightly. That difference matters when assessing the health of the industry. A vehicle producer can have a difficult month while factories making machinery, chemicals or other products perform better. For employees and suppliers, the distinction is practical rather than technical: a national manufacturing gain does not necessarily mean another shift has been added at an automotive plant. The report shows a concentrated setback, not a universal factory slump.
An Extended Summer Shutdown Hit Assembly and Parts Operations
Statistics Canada linked August’s decline to a prolonged summer shutdown at a major auto assembly plant. Its GDP release did not identify the facility, and the data alone cannot establish how many workers lost shifts or how long the interruption lasted. What is clear is that vehicle assembly activity was weaker than usual, with effects visible beyond the assembly line itself. Automakers purchase components, materials and services from a network of suppliers that must coordinate production with factory schedules.
A separate Statistics Canada manufacturing release reinforced that picture. Manufacturers’ sales of motor vehicles fell 4.0% in August, while motor vehicle parts sales declined 4.2%. The broader transportation equipment category recorded a 2.6% decline in sales, its second consecutive monthly decrease. Those are current-dollar sales figures rather than the real GDP measure behind the 5.8% headline, but both point to the same underlying disruption. A temporary stoppage is important; it is not, by itself, proof of a permanent production cut.
Dealerships Recover as New-Car Business Improves
The retail side of Canada’s auto economy moved in the opposite direction. Statistics Canada’s industry GDP figures show activity at motor vehicle and parts dealers rising 1.8% in August, more than reversing July’s decline. Higher activity at new-car dealerships drove that improvement. Across the entire retail sector, economic output increased 1.2%, providing one of the brighter contributions in an otherwise flat national economy.
The separate retail sales report adds useful detail but measures something different. Motor vehicle and parts dealers recorded a 1.2% increase in sales measured in current dollars, while new-car dealers saw sales rise 1.5% after a 1.4% July decline. Sales at used-car dealers actually slipped 0.5%. For a local sales team, that could mean a busier new-car showroom without an equally strong used-car department. The 1.8% and 1.2% dealership figures therefore are not competing estimates; one concerns real economic output, the other sales revenue. This distinction highlights the different conditions within automotive retail.
Wholesale Distributors Reveal a Third, Weaker Signal
Between an assembly plant and a retail dealership sits another part of the business: vehicle and parts wholesalers. Their economic output declined 4.4% in August, the first contraction in seven months. Statistics Canada linked the weakness to lower imports of passenger cars and light trucks, alongside unusually low manufacturing activity. Overall wholesale trade GDP fell 1.4%, making it the largest drag on economic growth that month.
Another government dataset showed wholesale sales of vehicles and parts slipping 3.8% to $15.1 billion. Within that figure, motor vehicle wholesalers’ sales declined 4.6% to $12.1 billion, and inventories across the vehicle and parts wholesale subsector fell 3.7%. These measures describe revenue and stocks rather than the 4.4% real GDP change, but they reinforce the need to look beyond showrooms. A dealer can sell more vehicles during a month when distributors move fewer new units into the system. The difference may reflect timing, inventory and imports rather than a single national trend.
August’s Setback Follows a Powerful Second-Quarter Rebound
The August manufacturing decline came after a striking recovery earlier in 2026. Statistics Canada reported that real motor vehicle manufacturing output jumped 20.9% in the second quarter, while motor vehicle parts manufacturing rose 10.8%. Transportation equipment manufacturing increased 8.4% over the same period. That was a sharp reversal from earlier weakness and helped lift overall manufacturing GDP by 2.1% in the quarter.
The rebound, however, did not return Canadian auto production to its 2023 level. Statistics Canada attributed part of the earlier weakness to semiconductor shortages late in 2025 and extended plant shutdowns for retooling and model changes in early 2026. Those factors make the latest figures especially important to interpret carefully. Monthly shutdowns can create dramatic swings when activity resumes or pauses again. For a parts supplier planning staffing and deliveries, a strong three-month period can help, but it cannot eliminate uncertainty about the next production schedule. August suggests the recovery remained uneven.
New Vehicle Sales and EVs Add Another Layer
The country’s vehicle sales figures confirm that consumers were still buying new cars and trucks, even as domestic production weakened. Statistics Canada counted 174,611 new vehicles sold across Canada in August, up 4.9% from August 2025. The dollar value of sales grew 8.8% year over year. These comparisons cover the same calendar month a year apart, not the seasonally adjusted monthly GDP changes used in the headline.
Electrified models also contributed to a changing showroom mix. Canadians purchased 22,716 new zero-emission vehicles in August, an increase of 55.1% from a year earlier. That category includes battery-electric and plug-in hybrid vehicles, which together represented 13.0% of new vehicle sales, up from 8.8% in August 2025. The numbers help explain why dealers might see opportunity even when Canadian assembly plants face setbacks. They do not establish where those vehicles were manufactured or prove that EV demand caused the monthly dealership GDP gain. Retail demand and domestic production are related, but separate.
Canada’s Factories Serve a Market Much Bigger Than Canada
Stronger domestic dealerships do not automatically create stronger demand for Canadian assembly plants. The federal government estimates that more than 90% of Canadian-made vehicles and 60% of Canadian-made auto parts are exported to the United States. Canadian factories therefore depend heavily on production plans and customers outside the country’s borders, while Canadian dealers can sell vehicles made in several different countries.
Statistics Canada’s research makes that dependence more concrete. Using 2024 data, it estimated that U.S. demand accounted for 76.4% of the value added and payroll jobs in Canada’s automobile and light-duty vehicle manufacturing industry, including roughly 27,000 jobs tied to U.S. exports. The report also found that more than 93% of Canada’s motor vehicle exports went to the United States in 2025. A sales manager in Toronto and an assembly worker in Windsor can thus experience the same month differently. One responds to Canadian buyers; the other is also exposed to cross-border production decisions, trade rules and demand.
Ontario Communities Have More at Stake Than a Monthly Percentage
For communities built around vehicle production, a decline in factory activity is more than a line on a national chart. Ontario accounted for 84.6% of Canadian employment in motor vehicle, body, trailer and parts manufacturing in 2024, according to the federal Job Bank. The province had about 148,300 people working across that broad sector that year. Roughly two-thirds of those workers were employed in parts manufacturing rather than vehicle assembly.
That structure helps explain why an assembly interruption can be felt far beyond one plant gate. Parts producers, logistics providers and local businesses may have to adapt when production schedules change. A supplier considering overtime or staffing cannot base its decision only on how well cars are selling at nearby dealerships. However, August’s 5.8% industry GDP decline cannot be translated directly into a job-loss figure, and Statistics Canada’s release did not do so. It measures the output setback, not its precise effect on individual households. This distinction matters when discussing risks to workers.
Other Manufacturers Kept the Overall Sector Growing
Canada’s entire manufacturing sector did not shrink alongside its auto industry. Real manufacturing GDP rose 0.3% in August, the fifth monthly increase in seven months. Machinery manufacturing expanded 3.8%, while petroleum refining activity grew 4.2% as some facilities resumed operations following maintenance. Those gains helped outweigh weakness in transportation equipment manufacturing, where the auto-related downturn was concentrated.
Other measures show why a single headline can be misleading. Statistics Canada’s manufacturing survey reported that factory sales across all industries increased 1.5% to $79.9 billion in August. But those are current-dollar sales: when measured in constant dollars, total manufacturing sales were essentially unchanged. The numbers are not inconsistent with the separate 0.3% increase in manufacturing GDP, because shipments and industry value added are different measures. For automotive businesses, the wider sector’s resilience provides useful economic context, but it offers little reassurance unless assembly orders, parts demand and plant schedules stabilize. Strength elsewhere cannot substitute for a working production line.
September and November Releases Will Test the Recovery
The next set of economic figures will help show whether August was primarily a temporary production interruption or part of a more persistent slowdown. Statistics Canada’s advance estimate suggests real GDP slipped 0.1% in September after remaining essentially unchanged in both July and August. Its early industry figures imply growth of 0.3% for the third quarter, measured quarter over quarter, although those estimates are subject to revision.
There are mixed early signals elsewhere. Preliminary September wholesale sales rose 0.5%, with motor vehicles and parts among the contributors, while advance retail sales pointed to a 0.7% increase. Those are current-dollar sales indicators, not proof that auto manufacturing recovered. Official September manufacturing and wholesale data are scheduled for November 13, retail sales for November 20, and GDP by industry for November 30. For factory workers, dealership operators and suppliers, the important question is whether production and sales begin moving together again, rather than merely offsetting one another in the national figures.
