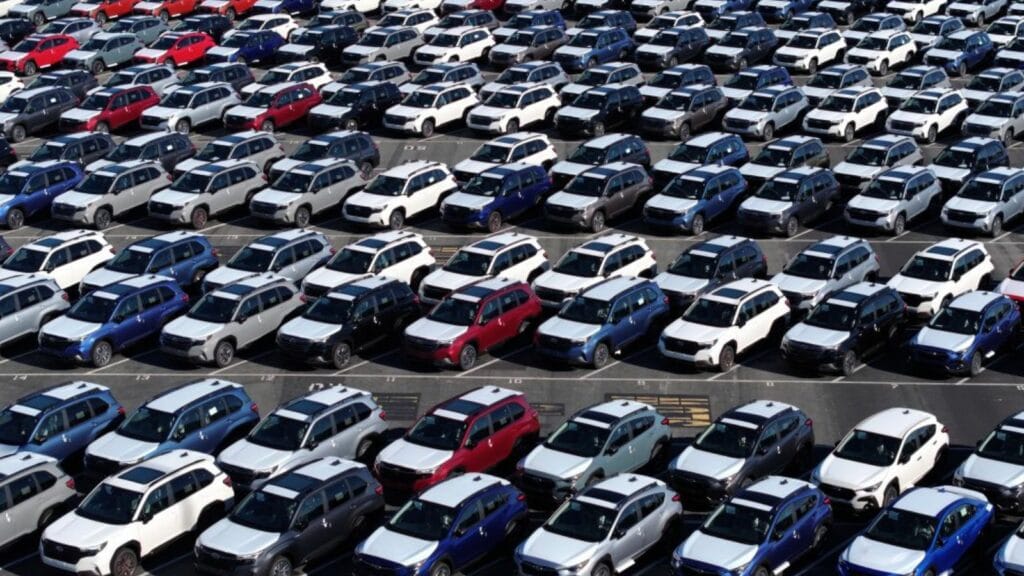
The country stamped on a vehicle’s build sheet is becoming far more important in Canada than it was only a year ago. U.S.-assembled vehicles accounted for 28.4% of Canadian new-vehicle sales in the first half of 2026, down from 35.4% in the same period of 2025 and well below the roughly 40% share they held from 2021 through early 2025.
The change does not mean Canadians suddenly stopped buying American brands. It reflects a deeper reshuffling of supply as tariffs make some U.S.-built models more expensive to bring north while automakers redirect Canadian inventory from Mexico, Japan and South Korea. The result is a market where the badge on the grille may look familiar, but the factory behind it is increasingly somewhere else.
A Seven-Point Share Loss in Just One Year
The 28.4% figure is striking because the broader Canadian market did not shrink by anything close to the same magnitude. DesRosiers Automotive Consultants estimated that roughly 950,000 new light vehicles were sold in Canada during the first six months of 2026, down 2.6% from about 976,000 a year earlier. Against that modest overall decline, the U.S. share of sales by assembly origin dropped seven percentage points. That makes the change much more than a simple reflection of weaker demand. It shows that the composition of what Canadians are buying has shifted sharply.
For several years, U.S. factories supplied roughly four in every 10 vehicles sold in Canada. By early 2026, that long-standing pattern had broken. The important distinction is assembly location rather than brand nationality. A Toyota, Honda, Hyundai or Subaru can be built in the United States, while a Ford or Chevrolet can come from Mexico or Canada. Tariffs have made that manufacturing map newly visible to dealers and buyers.
Tariffs Made Factory Location Matter Again
The shift began when the United States imposed a 25% tariff on imported automobiles effective April 3, 2025, under Section 232. For vehicles qualifying under CUSMA, the U.S. system allowed the tariff to apply to the vehicle’s non-U.S. content rather than necessarily its entire value. Canada responded on April 9 with a 25% surtax on non-CUSMA-compliant vehicles made in the United States and on the non-Canadian and non-Mexican content of CUSMA-compliant U.S.-made vehicles.
That structure created a powerful incentive for manufacturers to rethink which plants supplied Canadian dealers. A model built in Alabama or Indiana could face a different cost structure in Canada than a similar model coming from Mexico, Japan or South Korea. Ottawa also created a performance-based remission system that lets qualifying automakers with Canadian production import a defined number of U.S.-assembled, CUSMA-compliant vehicles without the counter-tariff, provided production and investment commitments are met. The result is not one uniform tariff wall, but a complicated sourcing equation that differs by model and manufacturer.
Mexico Has Become the Biggest Winner So Far
Mexico’s rise is the clearest mirror image of the U.S. decline. Vehicles assembled in Mexico accounted for 22.2% of Canadian sales in the first half of 2026, up from 18.3% a year earlier and 13.7% five years earlier. That is a remarkably fast change for an industry where factories, tooling and model programs are normally planned years in advance. Mexico is not replacing the United States model for model, but its large export-oriented assembly base gives automakers more options when they want to avoid exposure to Canadian counter-tariffs on U.S.-origin vehicles.
The shift was visible before the latest half-year figures arrived. Statistics Canada reported that imports of passenger cars and light trucks rose 6.9% in June 2025, largely because of higher imports from Mexico, just months after the tariff fight began. For Canadian shoppers, that can mean a familiar crossover or pickup arriving from a different North American plant than it once did. For manufacturers, using Mexican production can preserve inventory and pricing flexibility without abandoning the Canadian market.
Japan and South Korea Are Gaining Ground Too
The redistribution is not confined to North America. Japan’s share of Canadian new-vehicle sales climbed to 16.6% in the first half of 2026 from 13.7% a year earlier. South Korean-built vehicles reached 15.6%, about one percentage point higher than in the first half of 2025, while the share supplied from Europe was reported as largely unchanged. Together, those movements show how quickly global production networks can become a competitive advantage when one source country becomes more expensive.
The consumer experience can be subtle. A shopper may still walk into the same dealership and choose the same brand, yet the vehicle parked outside may have crossed the Pacific instead of the Canada-U.S. border. Hyundai offers a useful example: its Canadian supply has leaned more heavily on Mexico and South Korea, and the 2026 Santa Fe sold in Canada is sourced from South Korea rather than the United States. These changes are made upstream by manufacturers, meaning the sales statistics can shift even when brand preferences change much less dramatically.
Automakers Are Quietly Rewriting Their Canadian Supply Plans
Several manufacturers have responded by redirecting Canadian allocations rather than simply adding tariff costs to every vehicle. Industry reporting says Subaru shifted nearly all of its Canadian-market supply away from U.S. production toward Japan. Hyundai drew more heavily from Mexico and South Korea, while Mazda and Nissan reduced Canadian availability of some U.S.-built products. Those moves help explain why the decline in U.S.-assembled vehicles is so much steeper than the decline in total Canadian auto sales.
This is also why the story should not be reduced to Canadians deliberately rejecting U.S.-made vehicles. In many cases, shoppers never see the sourcing decision that happened months earlier. A dealer receives fewer units from one factory and more from another; a trim disappears; a model is delayed; or a replacement arrives from a different country. By the time the vehicle reaches the showroom, the tariff response has already been built into the inventory mix. Consumer choice still matters, but manufacturers are increasingly shaping the menu before the buyer arrives.
Canadian-Built Vehicles Did Not Automatically Fill the Gap
One might expect the U.S. decline to translate directly into a boom for Canadian-assembled vehicles, but that did not happen. Canadian-built models accounted for 11.5% of domestic new-vehicle sales in the first half of 2026, down from 12.6% a year earlier. J.D. Power Canada attributed part of that weakness to plant changeovers and lower output at some facilities. That is a reminder that domestic manufacturing capacity cannot instantly pivot to replace hundreds of thousands of imported vehicles.
Canada’s auto industry is also deeply export oriented. Federal figures say the country produced more than 1.2 million passenger vehicles in 2025, with more than 90% of Canadian-made vehicles exported to the United States. Canadian factories therefore exist inside a continental production system, not simply to stock Canadian dealerships. A plant may build a popular model, but most of its output can still be committed to the U.S. market. Tariffs can change those economics, yet production schedules, supplier contracts and model cycles make rapid reshuffling difficult.
Canada’s Remission Rules Split Automakers Into Two Camps
The difference between companies with Canadian factories and those without them is especially revealing. Ford, General Motors, Honda, Stellantis and Toyota all operate Canadian assembly plants and can qualify for Canada’s tariff-remission framework when they meet production and investment conditions. For those five manufacturers, U.S.-built vehicles still represented 45.2% of their Canadian sales in the first half of 2026, only 3.1 percentage points lower than a year earlier.
The change was far more severe among automakers without Canadian assembly operations. U.S.-made vehicles accounted for just 4.9% of their Canadian sales, down from 17.7% a year earlier. Ottawa extended the performance-based framework into a second year and established new quota volumes for April 9, 2026, through April 8, 2027. That makes Canadian production more than an industrial-policy issue; it directly affects how much U.S.-built inventory a manufacturer can bring into the country tariff-free. Two brands selling similar vehicles can therefore face very different sourcing pressures.
The Market Shift Has Helped Contain a Bigger Price Shock
Tariffs raised fears that Canadian vehicle prices would jump sharply, and those concerns helped pull some purchases forward in 2025. By the first half of 2026, however, the outcome was more complicated. AutoTrader reported that average new-vehicle prices in the first quarter were about $62,830, down 2.7% from a year earlier, while used prices averaged $36,713. Its second-quarter analysis again described industry-wide prices as easing modestly even though affordability remained a major problem.
That does not mean tariffs were harmless. Rather, manufacturers had several ways to absorb or avoid some of the pressure: changing source factories, adjusting model availability, using tariff remissions, altering incentives or accepting lower margins on selected products. Canadian light-vehicle sales were still down 2.6% in the first half of 2026, and affordability continued to weigh on buyers. Re-sourcing can therefore be understood partly as a defensive strategy—one intended to keep tariff exposure from flowing directly and fully into showroom prices while preserving enough inventory to compete.
The Bigger Risk Is to an Integrated North American Industry
The Canadian auto sector is too integrated with the United States to treat this as a normal import dispute. Federal data says the industry supports more than 125,000 direct jobs and more than 500,000 workers when the broader ecosystem is included, while contributing more than $16 billion annually to Canadian GDP. More than 90% of Canadian-made vehicles and roughly 60% of Canadian-made auto parts are exported to the United States. That dependence also runs the other way through parts, engines, components and finished vehicles moving across the border.
The Bank of Canada has warned that auto parts can cross the Canada-U.S. border several times during production, meaning tariffs applied at different stages can compound costs. Economic research on supply-chain tariffs reaches a similar conclusion: adjustment is possible, but it takes time and can cause substantial reallocation before any long-run gains appear. The sharp change in Canadian vehicle sourcing is therefore evidence of adaptation, but also of fragmentation in a system built for cross-border efficiency.
What Happens Next Depends More on Policy Than Brand Loyalty
J.D. Power Canada’s Robert Karwel has said Mexico could challenge the United States as Canada’s largest vehicle source in 2027 if current tariff conditions persist. That is a conditional industry view, not a certainty. July 2026 trade data already showed why the path may be uneven: Canadian imports of motor vehicles and parts jumped to a record, while imports of passenger cars and light trucks rose 19.8% on a seasonally adjusted monthly basis, with higher imports from the United States contributing to the gain.
For now, Canada’s 25% auto counter-tariffs on U.S.-origin vehicles remain in force, alongside the remission framework tied to domestic production. That keeps factory geography central to automakers’ decisions. If the tariff structure changes, sourcing could shift again quickly at the margin; if it persists, manufacturers have a stronger incentive to deepen the moves already visible toward Mexico, Japan and South Korea. The 28.4% figure is best read as a snapshot of a market being reorganized in real time, not as a permanent endpoint.
